
Subrogation After a Colorado Car Accident: What You Owe
Subrogation is your insurer’s right to recover what it paid on your crash claim from the person who caused the crash. In Colorado, that right has limits. Under C.R.S. § 10-1-135, an insurer or benefit plan generally cannot take a share of your injury recovery until you have been fully compensated. That is called the made-whole rule. It decides who gets paid first when a settlement is too small to cover everyone.
This guide explains how subrogation works after a Colorado car accident, which payers can come after your settlement, and the deadlines in the statute. It also covers how to answer a repayment demand without giving away money that belongs to you.
Table of Contents
- What subrogation means after a crash
- Why the made-whole rule matters most
- Who can ask for money back from your settlement
- The deadlines and paperwork in the statute
- How long a subrogation claim takes
- How to respond to a subrogation demand
- Mistakes that cost injured drivers money
- Our perspective
- When to bring in a lawyer
- Talk to our Colorado Springs team
- Frequently asked questions
- Sources
What subrogation means after a crash
Say a driver runs a red light in Colorado Springs and hits you. Your own insurer pays for your car repairs, or your health plan pays your emergency room bill. Neither company caused the crash, so each one steps into your shoes and tries to collect from the at-fault driver’s insurer. That is subrogation: “stepping into your place” to recover what was paid.
There are two versions, and people often mix them up:
- Property damage subrogation. Your auto carrier pays for your vehicle, then bills the at-fault driver’s carrier. This is usually handled between insurers, though your deductible can ride along in the demand.
- Injury-related reimbursement. A health plan, medical payments coverage or another payer covers your treatment, then asserts a right to be repaid out of your bodily injury settlement. This is the version that can shrink your take-home money.
The second kind is where most injured people get surprised. You settle, expect a check, and then a letter arrives from a plan you had nearly forgotten about, asking for a large share of it.
Our firm has written a separate overview of Colorado subrogation rules injury victims must know, and this article goes deeper on the car accident side.
Why the made-whole rule matters most
Colorado’s statute takes a clear position. It sets out the made-whole doctrine, which keeps an insurer from seeking reimbursement unless the injured person has been fully compensated for all of their damages, according to the text of C.R.S. § 10-1-135. The same statute treats a contract provision that demands reimbursement before you are made whole as void as against public policy.
In plain terms: a clause buried in a policy or plan booklet cannot override the rule for the payers the statute covers. If your damages are $200,000 and the only money available is a $100,000 policy limit, the statute is built so that you are not forced to hand part of that $100,000 back to a payer while you are still short.
What “fully compensated” really includes
Your damages in a car accident case are broader than medical bills. They can include:
- Past and future medical expenses
- Lost wages and reduced earning capacity
- Pain, suffering and loss of enjoyment of life
- Physical impairment or disfigurement
- Out-of-pocket costs such as rental cars, prescriptions and travel to treatment
Because the made-whole question compares your recovery to all of that, how your claim is valued has a direct effect on how much a payer can ask for. A claim that is documented thinly, or settled early at a low number, makes it harder to show you were not made whole. That is one reason we spend so much effort on valuation before any settlement conversation starts. Our Colorado car accident settlement guide covers how those numbers are built.
Who can ask for money back from your settlement
Not every payer plays by the same rules. After a Colorado crash, the usual claimants fall into these groups:
| Payer | What it may claim | Key point to know |
|---|---|---|
| Your health insurer (state-regulated plan) | Repayment of treatment costs it paid | Colorado’s made-whole statute is the main limit |
| Self-funded employer plan (ERISA) | Repayment under the plan’s own terms | Federal law can displace state rules, so the plan document matters |
| Medicare | Conditional payments it made | Federal rules, handled separately |
| Colorado Medicaid | Reimbursement of covered care | State and federal rules, handled separately |
| Medical payments (med-pay) coverage | Possible reimbursement depending on the policy | Read the policy and the statute together |
| Workers’ compensation carrier | Repayment if you were hurt on the job | Applies when the crash was work-related |
| Your auto insurer (collision) | Vehicle repair costs and your deductible | Usually pursued against the at-fault driver’s carrier |
Two of these deserve extra attention.
Self-funded ERISA plans
If your health coverage comes through an employer that pays claims from its own money rather than buying a policy from an insurer, federal law may apply instead of Colorado’s made-whole rule. Courts have enforced clear plan language that waives the made-whole doctrine. One federal appeals court, in Zurich American Insurance Co. v. Hara LLC, reasoned that protecting the financial health of such plans supports enforcing clear reimbursement terms.
That does not mean you simply pay whatever the plan demands. The plan document has to say what the plan claims it says. Amounts can still be negotiated, and the plan’s right can depend on whether it is truly self-funded. Our page on ERISA lien settlements in Colorado walks through the steps.
Medical payments coverage
Med-pay is the coverage on your own auto policy that pays medical bills after a crash regardless of who was at fault. People like it because it pays fast. The question to ask before you settle is whether your policy lets the carrier recoup those payments from your recovery. The answer depends on the policy language and the statute, so get the policy and read the reimbursement section before assuming either way.
It also helps to understand how your policy fits together with other coverage you carry. A broader look at personal versus commercial auto insurance shows why the type of policy involved in a crash changes who pays and who can ask to be repaid.
The deadlines and paperwork in the statute
The statute does not just say who wins. It also sets a process, and it has two 60-day clocks that matter.
According to C.R.S. § 10-1-135, if your recovery is less than your damages and you intend to enforce the made-whole protection, you must notify the payer within 60 days of each recovery. The payer then has 60 days from that notice to request arbitration.
That sequence has practical consequences:
- Track every recovery. A settlement with the at-fault driver’s insurer is one recovery. An underinsured motorist payment from your own carrier can be another. Each one can start its own clock.
- Put the notice in writing and keep proof. Send it in a way that creates a record, such as certified mail or a portal message with a confirmation.
- Expect a response. The payer may accept your position, negotiate, or ask for arbitration.
- Keep documents organized. You will want your settlement statement, the itemized lien or reimbursement notice, medical bills and your damages evidence in one place.
Miss the notice window and you give the payer room to argue you waived the protection. This is the sort of deadline that is easy to lose track of during a long recovery, when you are focused on healing and not paperwork.
How long a subrogation claim takes
Property damage subrogation between insurers can run on its own track while your injury claim moves forward. One large auto insurer says the average subrogation process takes about six months, and that complex or severe accidents can take longer.
For an injured person, what matters is how that timing meets your injury settlement:
- If your carrier is still pursuing recovery for your car, you may be waiting on your deductible.
- If a health plan has paid for treatment, it may send its reimbursement claim at any point, often after it learns a settlement is near.
- If you settle before the reimbursement amount is resolved, it is common to hold disputed funds in a trust account until the question is settled, rather than disbursing everything at once.
Ask early which payers have asserted a claim. Letting that surface only after a settlement is agreed leaves you with less leverage.
How to respond to a subrogation demand
A demand letter is an opening position, not a final bill. Here is a sensible order of operations.
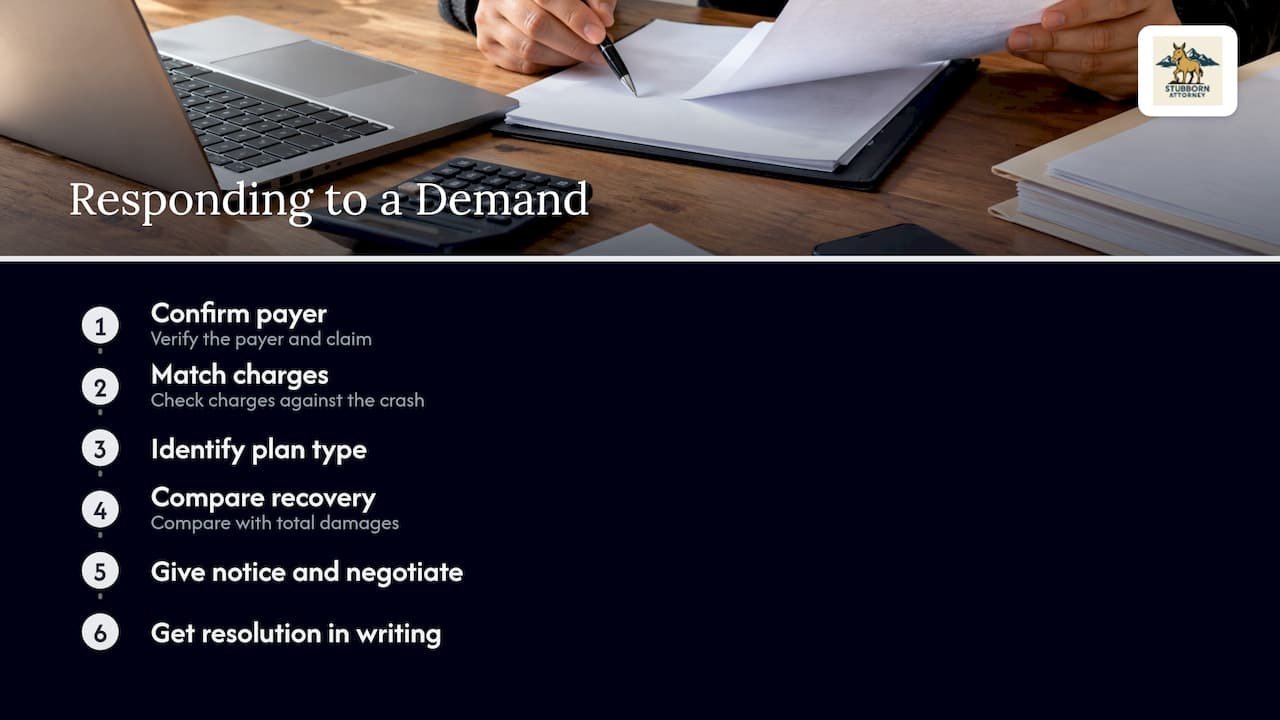
Step 1: Confirm who is asking and why
Identify the payer, the claim number, the dates of service and the total amount claimed. Ask for an itemized list. Plans sometimes include charges unrelated to the crash, such as treatment for an older condition.
Step 2: Match every charge to the crash
Compare the itemization with your records. Remove anything that predates the accident or is not related to your injuries. This step alone often reduces the number.
Step 3: Identify what type of plan it is
Is it a state-regulated policy, a self-funded ERISA plan, Medicare, Medicaid, med-pay or workers’ compensation? Each one has different rules, as the table above shows. The plan type tells you whether the made-whole statute helps you.
Step 4: Compare your recovery with your total damages
If your settlement is less than your full damages, the made-whole rule may limit what the payer can take. This is where a well-documented damages file matters.
Step 5: Give written notice and negotiate
Send the notice within the statutory window and open negotiations. Insurers tend to prefer a certain, smaller recovery now over the cost and uncertainty of a dispute, so reasonable reductions are often possible, especially when there are procedural defects, unrelated charges or a limited recovery. Do not assume the first number is the final one.
Step 6: Get the resolution in writing
Before any money moves, get a written agreement stating the final amount and that it fully resolves the payer’s claim.
If the offer on the table is far below what your case is worth, read our guide to what to do about a lowball insurance settlement in Colorado, because a low settlement and a high reimbursement demand compound each other.
Mistakes that cost injured drivers money
Few of these mistakes look serious when they happen. They show up later when you see the final numbers.
- Signing a reimbursement agreement early. Health plans and carriers sometimes send forms soon after treatment begins. Signing without understanding the terms can hand over rights the statute would have protected.
- Giving a recorded statement without preparation. What you say about your injuries and treatment can affect both the settlement and later reimbursement arguments.
- Settling before the picture is complete. If you are still treating, your damages are not yet known, and neither is the made-whole comparison.
- Ignoring letters from payers. A letter you do not answer does not go away. It can turn into a firm demand at settlement time.
- Assuming the at-fault driver’s policy limit is the end. Your own underinsured motorist coverage may add another source of recovery, and it can interact with the made-whole rules.
Understanding fault also helps, because it affects what you can recover in the first place. Our overview of fault in Colorado car accidents explains how responsibility is shared and why it matters to the size of a claim.
Our perspective
Most people who call us after a crash think the hard part is the other driver’s insurance company. Often the surprise comes later, when their own health plan or a benefit provider asks for money out of the settlement.
Before I practiced as an injury lawyer, I worked as a claims adjudicator for the federal government. I saw how large organizations evaluate a claim and a reimbursement request. They work from formulas and checklists, and they count on injured people not knowing what the statute protects.
That is why we look at the repayment question from the first week, not the last. We identify who has paid, what type of plan it is, and whether the made-whole rule helps our client. Then we build the damages case so the numbers support that position. We handle cases directly as attorneys, not as a case mill, because small details in a plan document can change what a client takes home.
Like the mule that gave this firm its new name, we keep walking the trail until the job is done. When we take a case, we do not let go.
Ryan
When to bring in a lawyer
You can answer a modest demand yourself. Bring in a lawyer when any of the following is true:
- A self-funded employer plan, Medicare or Medicaid is involved
- The reimbursement demand is a large share of the settlement
- Your damages exceed the available insurance, so you may not be made whole
- More than one payer has asserted a claim
- Fault is disputed or an underinsured motorist claim is in play
In these situations, the order in which claims are resolved and the way the notice is given can change the final result by thousands of dollars. Our guide on when to hire an automobile accident attorney lays out the signs in more detail, and our overview of types of car accident claims in Colorado shows which claims may be available to you.
We work on a contingency basis, so you pay nothing unless we recover money in your injury case.
Talk to our Colorado Springs team
If you were hurt in a crash in Colorado Springs or elsewhere in Colorado, and a payer is asking for repayment, we can review the demand and your coverage with you. We represent injured people only, across car, motorcycle, semi-truck, bicycle and pedestrian accidents, and we offer a free case review. See our car accident and injury services or start from our homepage to reach the team.
Frequently asked questions
Can my health insurer take part of my car accident settlement in Colorado?
Sometimes. Colorado’s made-whole statute generally keeps most state-regulated insurers and plans from taking repayment until you have been fully compensated. Self-funded ERISA plans, Medicare and Medicaid follow different rules, so the plan type decides the answer.
How long do I have to notify a payer under the Colorado statute?
If your recovery is less than your damages and you want to enforce the protection, the statute requires notice within 60 days of each recovery. The payer then has 60 days to request arbitration. Check the statute itself for the full wording.
Will subrogation delay my settlement?
It can. Reimbursement questions often must be resolved before funds are fully distributed, and one insurer estimates about six months on average for subrogation, longer in complex cases. Raising the issue early helps keep your case moving.
Can a reimbursement demand be negotiated?
Yes, in many cases. Unrelated charges, a limited recovery and procedural problems can all support a lower figure. Get any agreement in writing before money is paid.
Sources
- C.R.S. Section 10-1-135, Colorado Revised Statutes
- What is subrogation? Liberty Mutual
- Zurich American Insurance Co. v. Hara LLC (11th Cir. 2010)