
Uninsured Motorist Stacking in Colorado: How It Works
Stacking means combining the uninsured or underinsured motorist (UM/UIM) limits from more than one coverage source to pay for the same crash. In Colorado, whether you can do it depends on how your policies are written. A policy covering several vehicles under a single premium may be limited to applying once per accident. Separate policies are a different question, and the answer is not always yes.
This guide explains the Colorado rules in plain English, shows how stacking changes what you can recover with a worked example, and lists the steps that protect a UM/UIM claim after a crash. We are a Colorado personal injury firm, and these are the questions we get from injured drivers in Colorado Springs and across the state.
Table of Contents
- What stacking means under Colorado law
- How Colorado’s UM/UIM statute sets the baseline
- The anti-stacking rule for single-premium policies
- Stacking across separate policies
- What stacking can change in real dollars
- Other coverage should not shrink your UM/UIM benefits
- The claim process after a crash with an uninsured or underinsured driver
- Common stacking mistakes
- Perspective: why we read the policy before we talk numbers
- How we help with UM/UIM claims
- Questions to ask yourself before you call
- FAQ
- Sources
What stacking means under Colorado law
Colorado courts describe stacking as aggregating, combining, multiplying or “pyramiding” the limits of separate policies that provide uninsured and underinsured motorist coverage. The usual application is to put the limits of several policies on top of one another and draw on them until your damages are fully paid. The Colorado Court of Appeals described it this way in Bush v. State Farm, tying it to the UM/UIM statute, section 10-4-609.
Here is why it matters. UM/UIM coverage is the part of your own auto insurance that pays when the driver who hurt you has no insurance, or not enough. If your medical bills, lost income and pain and suffering come to $250,000 and the other driver carries only the minimum, your own UM/UIM limit is what stands between you and the shortfall. Stacking is a way to raise that ceiling when more than one policy is in play.
Two terms come up constantly:
- Uninsured motorist (UM): the at-fault driver has no liability insurance, or fled the scene and cannot be identified.
- Underinsured motorist (UIM): the at-fault driver has insurance, but the limits are too low to cover your damages.
Colorado’s statute treats underinsured coverage as part of uninsured motorist coverage. Section 10-4-609 defines it as coverage for bodily injury or death you are legally entitled to collect from the owner or driver of an underinsured motor vehicle. If you want the broader picture on dealing with a driver who has no coverage at all, our guide to uninsured driver claims covers it step by step.
How Colorado’s UM/UIM statute sets the baseline
Stacking only makes sense once you know what a single layer of coverage does. Three features of the statute shape everything else.
Coverage is offered unless you reject it in writing
Section 10-4-609 requires a Colorado auto liability policy to include uninsured motorist coverage for the people insured under it, unless the named insured rejects it in writing. A narrow exception exists for certain transportation network company coverage during a prearranged ride. The statute is published here. Many drivers do not remember signing a rejection form, so one early step is to ask your insurer for your declarations page and any signed rejection.
It fills the gap between the at-fault limits and your damages
The statute treats UM/UIM as a gap-filler. It covers the difference, if any, between the at-fault driver’s liability limits and the damages you sustained, excluding exemplary damages, up to the maximum UM/UIM coverage you bought. The coverage available may not be reduced by a setoff from other coverage. A 2026 Colorado Supreme Court opinion again described the system as person-based and designed to fill that difference, up to your purchased limits.
Coverage follows you, not the car
In Barnes v. State Farm, the Colorado Court of Appeals described the principle that UM coverage follows the person and not the vehicle. In practice, this is why a driver insured on one car can often claim UM benefits when hurt as a passenger, a pedestrian or a cyclist, depending on the policy. It is also the reason stacking questions arise: if the coverage belongs to you, the question becomes how many coverages belong to you and how they interact.
The anti-stacking rule for single-premium policies
The statute itself speaks to one stacking scenario directly. A single policy or endorsement for uninsured or underinsured motor vehicle coverage, issued for a single premium covering multiple vehicles, may be limited to applying once per accident.
Put simply, if you insure three cars on one policy and pay one UM/UIM premium, the insurer is allowed to write the policy so the coverage counts once, not three times. A $100,000 limit stays a $100,000 limit, even though three vehicles are listed.
This is the point where many drivers get confused. They see three cars on the declarations page and assume the coverage triples. Whether it does depends on the policy language and how the premium is charged. Look at three things on your declarations page:
- How many UM/UIM limits are listed. One limit for the whole policy, or a separate limit and premium line for each vehicle?
- The policy’s limit-of-liability wording. Look for language saying the coverage applies once per accident regardless of the number of vehicles.
- Any endorsements. Endorsements can change how limits combine.
If you cannot tell from the paperwork, that is a normal reason to have a Colorado attorney read the policy before you accept a settlement figure from your own insurer.
Stacking across separate policies
The harder question is whether you can combine coverage from separate policies, such as your own policy plus a spouse’s or a parent’s policy in the household. The Colorado Supreme Court addressed anti-stacking language in Shelter Mutual Insurance Co. v. Thompson. It held that an anti-stacking provision in underinsured motorist coverage does not violate public policy, and the insured there could not stack the benefits of six separate policies.
The lesson is not that stacking never works. It is that stacking depends on what each policy says, and Colorado courts have enforced clear anti-stacking wording. Other policies in your household may still matter for a different reason, since each may carry its own coverage that applies to you as an insured person. Sorting that out means collecting every policy that might cover you on the day of the crash.
A useful checklist of policies to gather:
- Your own auto policy, with the declarations page and all endorsements
- Any policy for a spouse or relative who lives in your household
- A policy for the vehicle you were in, if it was not your own
- Any employer or commercial policy, if you were driving for work
- Any umbrella policy, which may have its own UM/UIM terms
Do not assume any of these is irrelevant. Insurers do not always volunteer that another policy may apply, and adjusters typically evaluate the claim against the coverage you identify.
What stacking can change in real dollars
Here is an illustrative example. The numbers are made up to show the mechanics, not a prediction of any case.
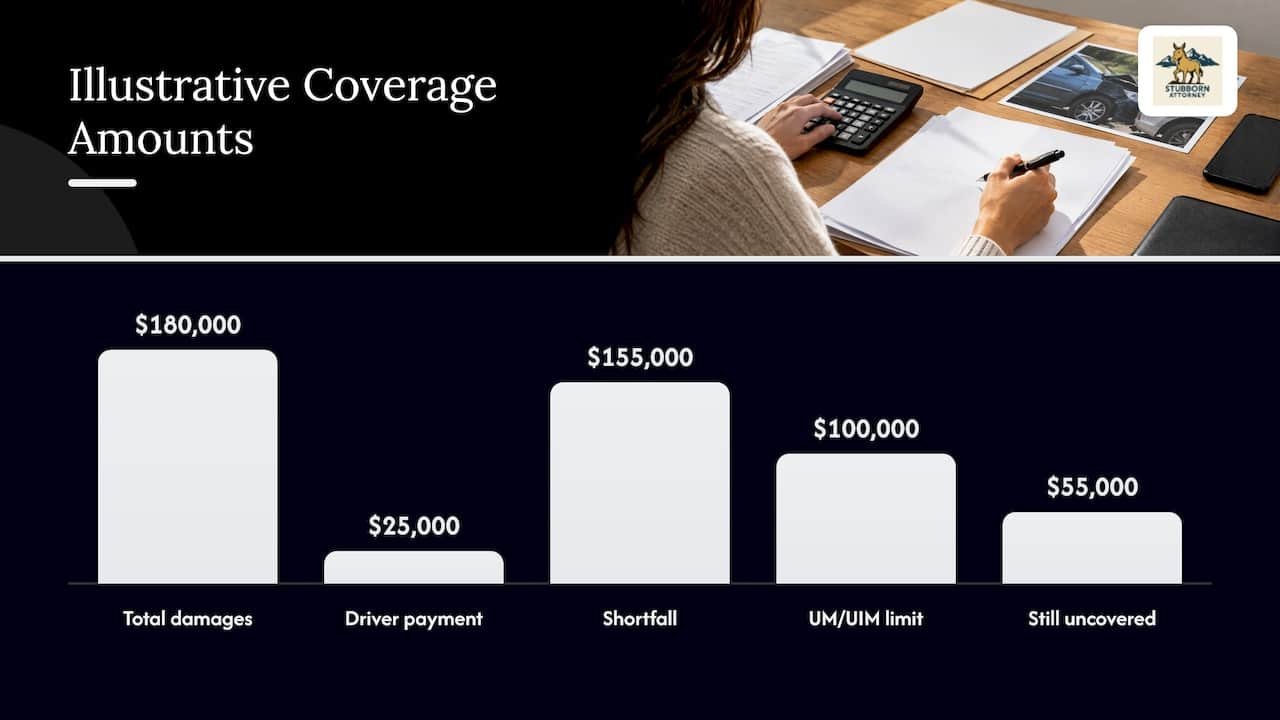
Imagine you are hurt by a driver whose liability limit is $25,000. Your documented damages come to $180,000. Your own UM/UIM limit is $100,000.
| Step | Amount |
|---|---|
| Your total damages | $180,000 |
| At-fault driver’s liability payment | $25,000 |
| Shortfall to cover | $155,000 |
| Your single UM/UIM limit | $100,000 |
| Still uncovered with one limit | $55,000 |
The gap-filling design means UM/UIM is measured against the difference between the at-fault limits and your damages, up to the limit you bought. With one $100,000 limit, you can run out of coverage before your damages are paid. If a second applicable coverage with its own limit is available to you and the policy wording permits combining, the uncovered amount may shrink or disappear. If the policy has an enforceable anti-stacking provision, it may not.
That is why reading the policy language matters more than counting cars.
Other coverage should not shrink your UM/UIM benefits
One protection works in your favor. The statute bars reducing your UM/UIM benefits by a setoff from other coverage. In Calderon v. American Family, the Colorado Supreme Court read the anti-setoff language to bar setting off MedPay payments against the amount paid under UM/UIM coverage. The court relied on the text of the prohibition and the policy behind it, concluding the legislature meant to prevent certain reductions of UM/UIM benefits because of payments from other coverages such as MedPay.
In practice: if you have MedPay and you are hurt by an underinsured driver, an insurer should not subtract your MedPay payments from what UM/UIM owes you under that holding. If an adjuster tries, raise it, and have an attorney review the math.
The claim process after a crash with an uninsured or underinsured driver
Stacking only helps if the claim is properly preserved. These steps matter most.
1. Get medical care and keep every record
See a doctor promptly, follow the treatment plan, and save bills, records and receipts. UM/UIM claims are measured by your damages, so documentation drives the number. If cost is keeping you from treatment, tell us when you call. Our firm’s position is that injured clients should have access to medical care regardless of their financial situation, and we can talk through how that works in your case.
2. Report the crash and identify the other driver’s coverage
Get the police report, the other driver’s insurance information, and photos of the scene. If the other driver has no insurance or fled, say so in the report. Our page on Colorado auto accident lawyers explains what victims should gather early.
3. Give your own insurer timely notice
Notice matters in UIM cases. In Clementi v. Nationwide, the Colorado Supreme Court said that when delayed notice is at issue, the insurer must prove prejudice by a preponderance of the evidence to deny benefits. Timeliness turns on whether notice was given within a reasonable time under the circumstances, measured from when the insured, with reasonable diligence, could tell the other driver was underinsured.
The same case is also a warning. The court agreed the insureds’ delayed notice was untimely as a matter of law, and sent the case back only because the record did not show whether the insurer was actually prejudiced. Waiting is a gamble you do not need to take. Notify your insurer of the crash and of a possible UM/UIM claim as soon as you know the other driver’s limits may fall short.
4. Collect every policy that might apply
Use the checklist above. Ask each insurer for a certified copy of the policy, not just the declarations page.
5. Be careful with recorded statements and releases
Your own insurer is also the party that pays the UM/UIM claim, so its interests and yours can pull apart. Before signing any release or giving a detailed recorded statement about fault and injuries, talk to a Colorado attorney. When an insurer handles a claim unreasonably, Colorado law offers remedies, which we discuss on our insurance bad faith page.
Common stacking mistakes
Drivers tend to trip on the same few points:
- Counting vehicles instead of limits. Three cars on one policy with a single premium may still mean one limit.
- Rejecting UM/UIM to save on premium. Coverage is required to be offered, and a written rejection can end the claim before it starts. The monthly savings are small next to a serious injury.
- Assuming the at-fault driver’s insurance is enough. State minimum limits rarely cover major medical bills. Our explainer on bodily injury liability in Colorado shows why the other driver’s limit is often the bottleneck.
- Waiting to notify the insurer. Late notice invites a dispute, as the Clementi case shows.
- Accepting the first offer. A quick payment from the at-fault insurer’s policy limit can affect your UIM claim, so get advice on consent and release terms first.
- Ignoring other household policies. A relative’s policy may apply to you as an insured person.
For a wider look at the different routes available after a crash, see our overview of car accident claim types in Colorado. And our article on seven vital facts about uninsured and underinsured motorist insurance covers the basics if you are new to the topic.
Perspective: why we read the policy before we talk numbers
Stacking questions look like math problems. They are really reading problems. The answer sits in the declarations page, the endorsements and the wording of the limit-of-liability clause, and most injured people have never seen those pages side by side.
Before joining the legal side of injury claims full time, I worked as a claims adjudicator for the federal government. I spent years inside the process insurers use to evaluate a claim, so I know how a file gets valued, what an adjuster looks for, and where a number can quietly come down. That experience shapes how we handle UM/UIM cases at Malnar Injury Law, now doing business under the Stubborn Attorney name.
Our approach is simple. We collect every policy that might apply, read the language for ourselves, and build the damages case so the number is supported by records, not hope. Cases at our firm are handled directly by attorneys, not passed through a volume operation. We have settled hundreds of injury cases, and we represent only injured people.
The mule on our brand is not decoration. A mule keeps walking when the trail gets steep. A UM/UIM claim against your own insurer can be a steep trail, and when we take a case, we do not let go.
Ryan
How we help with UM/UIM claims
If you were hurt by an uninsured or underinsured driver, we can review your policies, identify the coverage that may apply to you, and handle the claim with your insurer. We represent injured people in Colorado Springs and across Colorado in car, motorcycle, semi-truck, bicycle and pedestrian crashes, among other injury cases. Our work is on a contingency basis, so you pay no attorney fee unless we recover money in your case.
You can see the full list of practice areas on our services page. If you were hurt in a crash in the Pikes Peak region, start with our Colorado Springs car accident lawyer page and request a free case review. Not sure whether you need a lawyer yet? Read when to hire an automobile accident attorney.
Questions to ask yourself before you call
These make a first conversation faster and more useful:
- Who was driving, and whose vehicle was it?
- Did the other driver have insurance, and do you know the limits?
- How many policies list you, a spouse or a household relative as an insured?
- Did you ever sign a UM/UIM rejection form?
- Have you already given a statement or signed anything for any insurer?
- What medical treatment have you had, and what is planned?
- Have lost wages become part of the picture? Our guide to a Colorado lost wages claim explains how that portion is documented.
These answers tell us whether a stacking question exists in your case at all. Sometimes one policy is all there is, and the focus moves to proving damages. Sometimes a second policy changes the whole picture.
FAQ
Can I stack uninsured motorist coverage on multiple cars in Colorado?
Not automatically. Colorado’s statute allows a single policy or endorsement issued for a single premium covering multiple vehicles to be limited to applying once per accident. If each vehicle carries its own separately priced UM/UIM coverage, the answer may differ, so the policy wording decides.
Does uninsured motorist coverage cover me if I was a passenger or pedestrian?
Often, yes. Colorado courts have described UM coverage as following the person and not the vehicle, so it can apply when you are hurt outside your own car. The exact terms depend on your policy and who qualifies as an insured, so have the policy reviewed.
Can my insurer reduce my UM/UIM payment because I already received MedPay?
The Colorado Supreme Court has held that the statute’s anti-setoff language bars setting off MedPay payments from the amount paid under UM/UIM coverage. If an adjuster subtracts MedPay, ask an attorney to review how the figure was calculated.
How soon do I need to notify my insurer about a UIM claim?
As soon as you reasonably can. Colorado courts judge timeliness by what is reasonable under the circumstances, and an insurer must show it was prejudiced by delay to deny benefits. Even so, late notice invites a fight you can avoid by reporting promptly.
Does it cost anything to have a lawyer review my stacking question?
We offer a free case review, and we work on a contingency fee, so you owe no attorney fee unless we recover money in your case. Call us with your policy documents and crash details and we will tell you what we see.
Sources
- Bush v. State Farm Mutual Automobile Insurance Company, Colorado Court of Appeals (2004)
- Colorado Revised Statutes Section 10-4-609 (2025), Justia
- C.R.S. Section 10-4-609, Colorado Public Law
- Shelter Mutual Insurance Co. v. Thompson, Colorado Supreme Court (1993)
- Barnes v. State Farm Mutual Automobile Insurance Company, Colorado Court of Appeals (2021)
- Calderon v. American Family Mutual Insurance Company, Colorado Supreme Court (2016)
- Clementi v. Nationwide Mutual Fire Insurance Co., Colorado Supreme Court (2001)
- Colorado Supreme Court opinion 24SC440 (2026)