How Attorneys Calculate Loss of Earning Capacity and What Experts Do
Loss of earning capacity is a compensable, forward-looking economic loss that measures the permanent reduction in a person’s ability to earn after an injury. It is recoverable in personal injury claims when a plaintiff proves it by a preponderance of the evidence, not guesswork. Proving it typically takes three kinds of experts working together: a treating or examining physician, a vocational expert, and a forensic economist.
Table of Contents
- What Is Loss of Earning Capacity, and How Does It Differ From Lost Wages?
- What Legal Standard Applies to Loss of Earning Capacity Claims?
- Who Provides Evidence for a Loss of Earning Capacity Claim?
- How Is Loss of Earning Capacity Calculated?
- What Factors Increase or Decrease a Loss of Earning Capacity Award?
- What Records Should You Collect to Prove Your Claim?
- Why This Guidance Comes From Practical Case Experience
- How Do Pre-Existing Conditions Affect an Earning Capacity Claim?
- Total Loss vs. Partial Loss of Earning Capacity: What Changes?
- How Does the Insurance Claims Process Handle Earning Capacity Losses?
- How Long Does It Take to Evaluate and Resolve These Claims?
- Can Rehabilitation or Retraining Reduce a Loss of Earning Capacity Claim?
- What This Article’s Research Actually Tells You to Prioritize
- Get Help Building a Loss of Earning Capacity Claim
- Primary Sources and Jury Instruction Materials
- Sources
- FAQ
What Is Loss of Earning Capacity, and How Does It Differ From Lost Wages?
Three terms get thrown around as if they mean the same thing, and they don’t.
Lost wages covers income already missed between the injury date and trial or settlement. It’s the paycheck you didn’t get last month because you were in a hospital bed. Payroll records and pay stubs usually settle the question.
Loss of future earnings is sometimes used loosely as a synonym for earning capacity, but it more often refers to a specific, calculable stream of income you would have earned in a known job you actually held or were about to start.
Loss of earning capacity (LOEC) is broader and more permanent. It asks what you could have earned over a working lifetime, not what you would have earned in one particular job. A forensic economist’s analysis can support this claim even for someone with a thin work history, because capacity is about opportunity, not a resume.
- Lost wages: past, documented, exact.
- Loss of future earnings: projected, but tied to a specific career path.
- Loss of earning capacity: permanent, broader, and based on potential rather than a single job.
The distinction matters because courts calculate and instruct juries on these categories differently, and mixing them up in a demand letter weakens the claim.
What Legal Standard Applies to Loss of Earning Capacity Claims?
Juries don’t award damages on sympathy or speculation. Plaintiffs must prove loss of earning capacity by a preponderance of the evidence, meaning it’s more likely than not that the injury caused a real, lasting reduction in earning ability. Courts describe this as “reasonable probability” or “reasonable certainty,” not mathematical proof.
California’s model jury instruction, CACI No. 3903D, breaks the test into two parts: first, is it reasonably certain the injury will reduce future earnings, and second, what is the reasonable dollar value of that loss? Notably, the instruction doesn’t require the plaintiff to have a prior earnings history to qualify.
States vary in how they word this test and what expert testimony they’ll accept as sufficient. Some benchbooks, including federal Longshore Act guidance, direct fact finders to weigh actual post-injury wages first, then fall back on a broader capacity estimate if those wages don’t fairly reflect what the person can still earn. Check your jurisdiction’s specific instructions or talk to counsel before assuming one state’s rule applies to your case.
Who Provides Evidence for a Loss of Earning Capacity Claim?
Three types of experts typically build a loss of earning capacity claim, each covering ground the others can’t.
- Medical experts establish permanence: what physical or cognitive limits remain, what the prognosis is, and what objective findings (imaging, functional capacity exams) support those restrictions.
- Vocational experts translate medical restrictions into real job market terms: what jobs remain realistic, what transferable skills exist, and whether those jobs are actually available in the local labor market.
- Forensic economists turn all of that into dollars: annual loss amount, work-life expectancy, and the discount rate applied to future sums.
Supporting documents matter too: payroll history, tax returns, employer letters describing promotion tracks, and education or training records that show where a career was actually headed.
Pro Tip: Ask your vocational expert for actual job postings in your labor market that match your post-injury restrictions, not just a theoretical job title. Juries respond to concrete listings far more than abstract labor statistics.
How Is Loss of Earning Capacity Calculated?
The core formula economists use is straightforward: (projected pre-injury earnings minus projected post-injury earnings) multiplied by work-life expectancy. The hard part is populating each variable correctly.
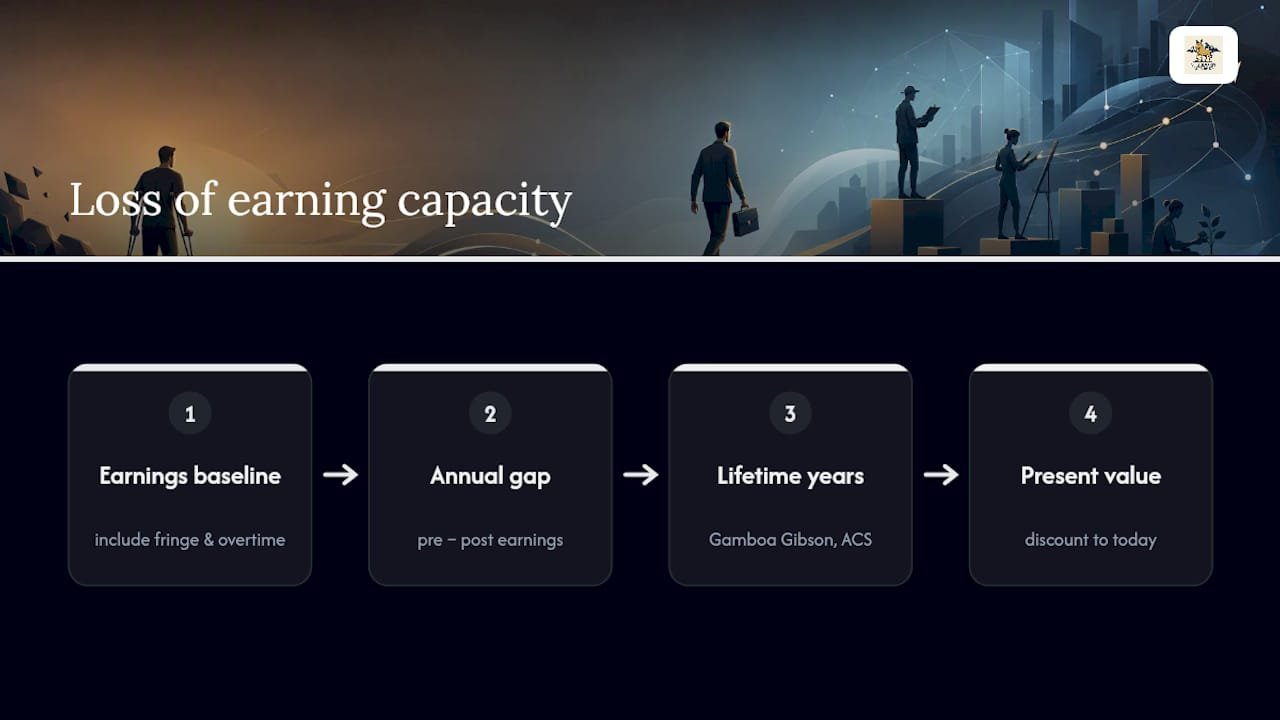
Work-life expectancy isn’t just “years until retirement.” Economists typically pull from labor statistics tables, including the Gamboa Gibson Worklife Tables and American Community Survey data, to estimate how many years someone with a similar age, education, and health profile would realistically have remained in the workforce. Fringe benefits (health insurance, retirement contributions) and overtime patterns get added into the earnings baseline when they were a documented, recurring part of the job.
Courts then require discounting that projected loss to present value, meaning the lump sum is reduced to reflect what it’s worth today rather than paid out year by year. This prevents a windfall: a dollar received now can earn interest, so the award has to account for that. Juries are also generally instructed not to award losses beyond a realistic retirement age.
A forensic economist becomes close to essential in catastrophic injury cases or when a career trajectory was genuinely uncertain, since the assumptions behind the math get picked apart hard at deposition.
What Factors Increase or Decrease a Loss of Earning Capacity Award?
Age matters enormously. A 28-year-old engineer with 35 remaining work years carries a much larger theoretical loss than a 61-year-old close to retirement, even with an identical injury.
- Career trajectory: A worker on a documented promotion track, with performance reviews and raise history to back it up, can claim more than someone with a flat earnings history.
- Overtime and bonuses: These count toward the loss calculation only when they were a consistent, provable part of past income, not occasional extras.
- Business owners: Profits only count as personal earning capacity when they reflect the owner’s own labor, not capital investment or employees’ work. A shop owner whose income comes mostly from three employees’ labor has a weaker earning-capacity claim than a solo contractor whose income is pure personal output.
- Illustrative scenarios: a young professional passed over for a promotion track after a spine injury; a tradesperson with a permanent lifting restriction who can no longer do the physical job; a catastrophic injury resulting in total, permanent loss of any earning ability.
What Records Should You Collect to Prove Your Claim?
Start gathering documentation the moment you know an injury might affect your work long term. Waiting until settlement talks begin means missing records that get harder to reconstruct later.
- Payroll stubs, W2s or tax returns, and any employer letters describing your role, raises, or promotion path.
- Performance reviews and job postings for the position you were on track to reach.
- Medical records, functional capacity testing, and written restrictions from treating providers.
- A log of job searches, retraining attempts, and other mitigation efforts, since courts expect reasonable, not extraordinary, effort to find suitable work.
Retain a vocational expert once medical restrictions are stable enough to define real job limitations, and bring in an economist as soon as the case looks like it will exceed a straightforward past-wage claim. A checklist of evidence built early keeps the file organized when experts need it.
Pro Tip: Save copies of actual online job postings that match your pre-injury role and your realistic post-injury restrictions the same week you find them. Listings disappear, and a printed snapshot dated near the injury carries more weight than a recreated search months later.
Why This Guidance Comes From Practical Case Experience
Ryan Malnar has spent more than a decade representing injury victims, and before that, worked as a federal claims adjudicator and adjuster. That combination matters here: it means knowing how the other side builds its counterarguments against a loss of earning capacity claim before they make them.
Malnar Injury Law, now operating as Stubbornattorney, has settled hundreds of injury cases and recovered millions of dollars for clients. That practitioner history shapes how the firm selects vocational experts and forensic economists, and how it times settlement negotiations around the present-value calculations insurers routinely try to lowball.
How Do Pre-Existing Conditions Affect an Earning Capacity Claim?
A pre-existing condition doesn’t erase a loss of earning capacity claim, but it does complicate the math. Insurance defense attorneys will argue that a prior back injury, a degenerative condition, or an old workplace restriction already limited your earning capacity before this accident happened at all.
The legal principle that usually protects claimants here is the idea that a defendant takes the plaintiff as they find them. If you were working full duty, earning full pay, and managing a pre-existing condition without limitation before the accident, you can still recover for the additional loss the new injury caused. The comparison isn’t between “perfect health” and your current state. It’s between your actual pre-accident earning capacity and your post-accident earning capacity.
Medical experts play an outsized role in these cases because they have to draw a credible line between what the old condition already limited and what the new injury made worse. A treating physician’s notes from before the accident become critical evidence, showing you were functioning at full capacity despite the pre-existing issue.
Vocational experts and economists then have to build two models: one representing your capacity as it stood right before the accident, and one representing it after. The gap between those two models, not the gap between you and a hypothetical uninjured person, is what the claim is worth.
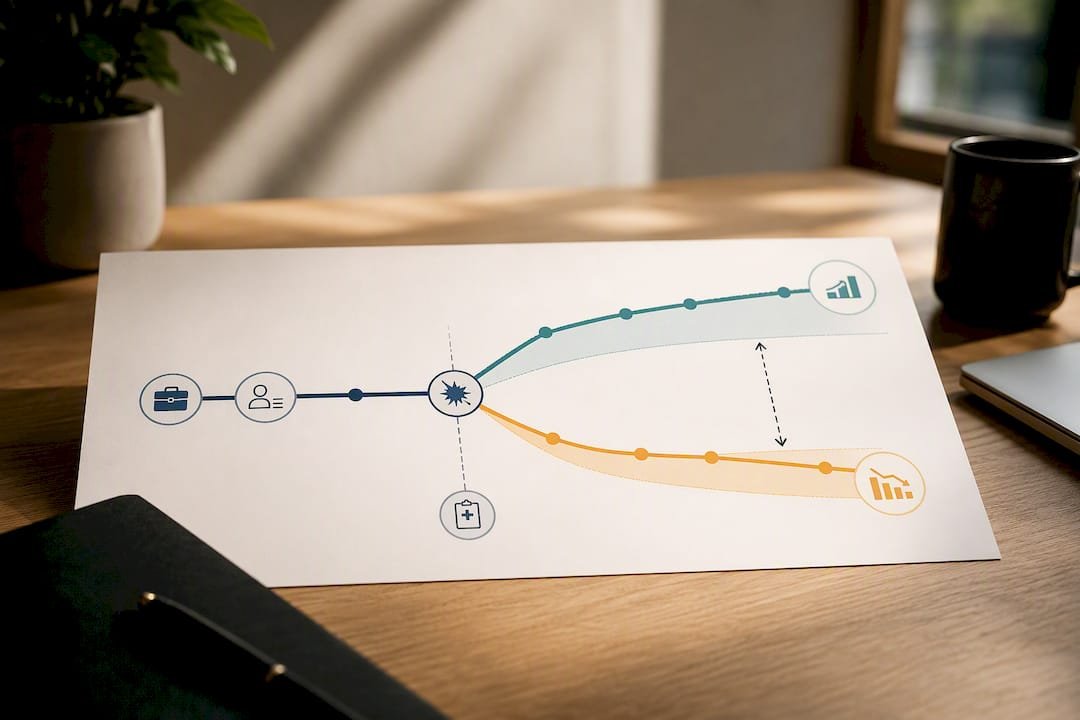
This is one of the most heavily litigated aspects of earning capacity claims, and it’s also where thin documentation hurts the most. Old medical records, past performance reviews, and prior earnings history all become evidence you’ll wish you’d kept.
Total Loss vs. Partial Loss of Earning Capacity: What Changes?
A total loss of earning capacity means the injury eliminates any realistic ability to earn income in any occupation the person is qualified for, given their age, education, and training. This is the category reserved for catastrophic injuries: severe brain injuries, high-level spinal cord damage, amputations affecting multiple limbs. The calculation is comparatively simpler because there’s no post-injury earnings figure to subtract. The formula essentially becomes pre-injury projected earnings times work-life expectancy, discounted to present value.
A partial loss is far more common and far more contested. It applies when someone can still work, just not at the same level, in the same field, or for the same pay. A construction foreman who can no longer lift more than 20 pounds but can work a desk job in the same industry has a partial loss. So does a surgeon who develops a tremor and has to shift into a lower-paying consulting role.
Partial loss cases hinge heavily on vocational testimony because the dispute usually isn’t whether income dropped. It’s whether the person could have earned more with different effort, training, or job search strategy. Insurance defense teams routinely argue that a partial-loss claimant hasn’t mitigated damages aggressively enough, which is why documentation of real job searches and retraining attempts carries so much weight in these disputes.
The dollar difference between how total and partial claims get valued can be enormous, which is exactly why insurers push hard to reclassify a claim from total to partial whenever the medical record leaves any room to argue it.
How Does the Insurance Claims Process Handle Earning Capacity Losses?
Insurers evaluate loss of earning capacity claims differently than they evaluate straightforward lost-wage claims, and slower.
A lost-wage claim is arithmetic: missed paychecks times missed weeks, verified by an employer. An earning capacity claim requires the insurer’s own claims examiner, and often their own retained vocational or medical expert, to evaluate projections rather than receipts. That means more back-and-forth, more requests for records, and more skepticism baked into the initial offer.
Adjusters typically request full medical records, wage history going back several years, and sometimes an independent medical examination (IME) performed by a doctor the insurer selects. Expect early settlement offers to undervalue the capacity component specifically, since it’s the hardest piece for an adjuster to quantify without pushback. Adjusters are trained to challenge projections that rely on “what might have been” rather than documented facts, which is precisely why vocational and economic expert reports matter so much at this stage.
Claims involving a forensic economist’s report tend to move slower through the insurance side because the adjuster’s own expert has to review and often counter the assumptions (growth rates, discount rates, work-life tables) baked into that report. This is also the stage where a demand package with organized documentation, rather than a vague narrative, tends to produce a meaningfully better opening offer. A well-supported damages breakdown at this stage sets the tone for the rest of negotiations.
How Long Does It Take to Evaluate and Resolve These Claims?
Loss of earning capacity claims almost always take longer to resolve than straightforward lost-wage claims, largely because the medical picture has to stabilize before anyone can credibly project a permanent loss.
Doctors typically wait until a patient reaches maximum medical improvement (MMI), the point where further recovery isn’t expected, before issuing permanent restrictions. Depending on injury severity, that can take anywhere from a few months to well over a year. Vocational and economic experts generally can’t build a reliable projection until MMI is reached, since an earlier estimate risks being wrong in either direction.
Once MMI is documented, gathering vocational and economic expert reports typically adds a few more months. Litigated cases, where the insurer disputes the capacity claim outright, stretch the timeline further, sometimes into a year or more once depositions of the competing experts are factored in.
Simpler partial-loss cases with clear, consistent medical restrictions and an available post-injury job comparison tend to resolve faster than total-loss or heavily disputed partial cases, where both sides bring in competing experts who reach very different numbers.
Can Rehabilitation or Retraining Reduce a Loss of Earning Capacity Claim?
Yes, and this is one of the more misunderstood parts of these claims. Successful rehabilitation and retraining don’t eliminate a valid earning capacity claim. They narrow the gap the claim is measuring.
If a warehouse worker with a permanent shoulder injury completes a retraining program and lands a logistics coordinator role at 80% of his old pay, the claim shifts from “total incapacity” math to a partial-loss calculation based on that remaining 20% gap, plus whatever career ceiling difference the injury still imposes long term.
Courts and juries generally view genuine retraining efforts favorably, since it demonstrates the reasonable mitigation standard courts expect. It doesn’t punish claimants for trying. What it does is require the vocational expert’s model to be updated with real, current data rather than a purely theoretical pre-injury projection. That updated model becomes the more credible number precisely because it’s grounded in what actually happened.
The strategic mistake some claimants make is assuming retraining success will hurt their case, so they avoid documenting it. It’s the opposite: a well-documented retraining effort, even a partially successful one, strengthens credibility with a jury far more than an untested claim that no effort was made at all.
What This Article’s Research Actually Tells You to Prioritize
Here’s what gets lost in most explanations of loss of earning capacity: the legal standard is genuinely lenient (reasonable probability, not certainty), but the practical bar is high, because juries and adjusters both punish claims that feel speculative. The gap between those two realities is where most cases lose value.
Conventional advice tells claimants to “document everything,” which is true but useless without prioritization. If you take one thing from this walkthrough, it’s this: the earliest medical restriction notes and the earliest job postings you can save are worth more than volume. A single dated job posting from the week of your injury, matched against your actual restrictions, often carries more weight with an adjuster than a folder of generic labor statistics.
The other underrated point is timing on experts. Waiting until litigation to bring in a vocational expert or economist means losing months where memory, records, and job market snapshots were fresher. Retaining the right expert early doesn’t just build the number. It builds the credibility of the number, which is what actually moves a settlement offer.
— Ryan
Get Help Building a Loss of Earning Capacity Claim
Proving loss of earning capacity means coordinating medical, vocational, and economic testimony into one number an insurer can’t easily dismiss, and that coordination is exactly what an attorney handles day to day. Stubbornattorney selects the right experts for your specific injury and career trajectory, assembles the documentation adjusters actually respect, and pushes back when an insurer’s present-value math tries to lowball a permanent loss.
The firm works on a contingency fee basis, so clients typically pay nothing unless there is a recovery, and a free case evaluation is offered. If you’re dealing with a serious injury affecting your ability to work, consider seeking a free consultation to discuss your claim before accepting an early settlement offer.
Primary Sources and Jury Instruction Materials
For readers or attorneys who want to review the underlying legal materials directly: the Cornell Legal Information Institute explains the preponderance standard; Justia publishes the CACI No. 3903D jury instruction; the Department of Labor’s LHWCA benchbook covers wage-earning capacity analysis; and Plaintiff Magazine and Nolo offer practical breakdowns of proof and calculation methods.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Preponderance of the evidence — Legal Information Institute (Cornell Law)
- Damages for loss of earning capacity: What could have been — Plaintiff Magazine
- How do I prove future lost earnings in a personal injury case? — Nolo
- CACI No. 3903D. Lost Earning Capacity (Economic Damage) :: Justia
FAQ
What Is the Difference Between Loss of Future Earnings and Loss of Earning Capacity?
Loss of future earnings usually refers to a projected income stream tied to a specific job or career path, while loss of earning capacity is the broader, permanent reduction in overall ability to earn across any suitable occupation.
How Do You Calculate Loss of Wage Earning Capacity?
The standard approach subtracts projected post-injury earnings from projected pre-injury earnings, multiplies the result by work-life expectancy, and then discounts that total to present value.
What Does Earning Capacity Mean in a Legal Claim?
Earning capacity means what a person could realistically earn given their age, education, skills, and health, not necessarily what they were earning at the time of the injury.
How Is Loss of Earnings Calculated After an Injury?
Past lost earnings are calculated from documented pay records between the injury and resolution, while future and capacity-based losses require medical, vocational, and economic expert projections discounted to present value.
Do I Need a Lawyer to Prove Loss of Earning Capacity?
You don’t legally need one, but proving this type of claim requires coordinating medical, vocational, and economic expert testimony, which is where firms like Stubbornattorney typically add the most value for claimants.